Our take on the latest Economic and fiscal update (Tue 16 Dec 2025)
Core Crown revenue down $6.3b, and expenses up $0.5b
Return to surplus now in 2029/30 (OBEGALx)
80% of the increase in net Core Crown debt to fund capex
The key numbers...
- Tough economic conditions in 2025 have weighed on The Treasury’s forecasts, resulting in economic growth picking up later than expected in May’s Budget 2025. Annual growth in real GDP is expected to turn positive (+0.2%) in the final quarter of 2025, a quarter later than previously expected. Growth is expected to reach 3.0%pa by the end of 2026, driven by lower interest rates and strong export returns.
- Expectations for Core Crown expenses have risen, up $0.5b over the 2026-2029 period. These increased expenses are largely due to higher inflation expectations, which keep spending above 30% of GDP throughout the period to 2030.
- Forecast Core Crown revenue has fallen $6.3b over the 2026 to 2029 period, with a lower tax take driven by the government’s Investment Boost policy, along with lower resident withholding tax due to interest rates that are lower than previously expected.
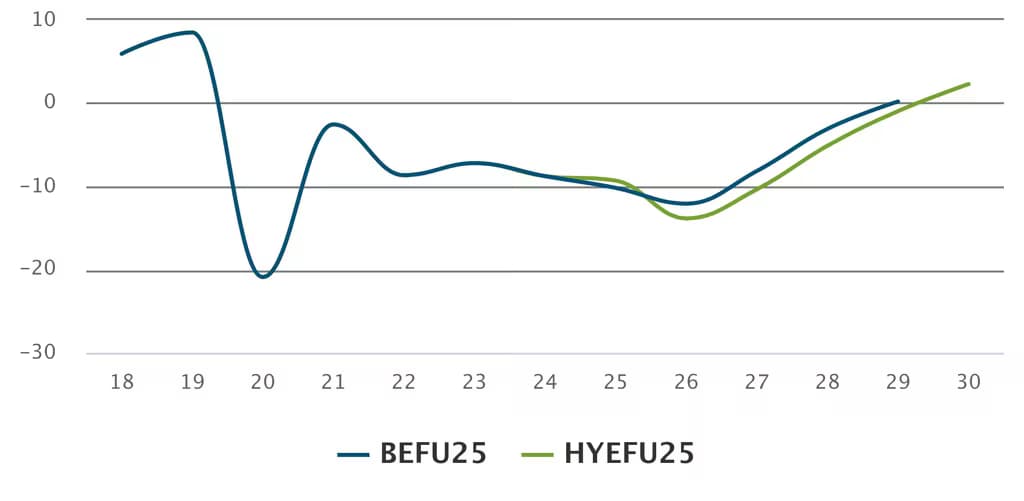
- The combination of lower revenue and slightly higher spending results in the operating balance before gains and losses excluding ACC (OBEGALx) not being forecast to turn from deficit to surplus until 2029/30, a year later than forecast in Budget 2025.
- Net core crown debt is lower in the near term driven, as the NZ Government Bond programme is set to be $3b lower for 2025/26and $2b lower for 2026/27. However, larger fiscal deficits over the medium term are set to drive issuance higher in 2027/28 and 2028/29, with both years having been revised higher by $4b.
- Of the $72b increase in net Core Crown debt over the forecast period, around 80% is to fund capital expenditure, which still leaves $14b of operating spending needing to be funded by debt.
Return to surplus pushed out a year to 2029/30
$b, OBEGAL (excl ACC)
...and our reaction
- Weak economic conditions in 2025 are weighing on near-term forecasts of economic growth, but the potential for significant revisions to previous GDP figures in the September 2025 quarter GDP released later this week might help boost near term growth. Treasury’s forecasts incorporate economic data up to 24 October 2025, with forecast quarterly GDP growth of 0.4% for September, substantially below current market expectations of 0.9% (seasonally adjusted).
- Treasury sees risks to its own forecasts as largely balanced, as opposed to the Budget 2025 forecasts, where the risks were skewed to the downside due to the “Liberation Day” tariff announcement prior to the release of the Budget.
- Treasury’s forecasts for house price growth, net migration, and residential investment continue to be materially above our expectations throughout the forecast period. Underperformance against these key indicators present a downside risk to Treasury forecasts for growth and tax revenue.
Latest updates
Premium
Economic and fiscal update
More money, more problems for political parties
Tue 29 Sept 2026
 $2.06b Government surplus a year earlier, in 2029
 $12.5b Government revenue over 2027-30, relative to BEFU 2026
 Government debt 44% of GDP in 2028, 2ppts lower than in BEFU 2026
Premium
Economic and fiscal update
Budget 2026: Fiscal position set to improve
Thu 28 May 2026
$3b Surplus a year earlier in 2030$10.8b Higher revenue over 2026-30, relative to HYEFU$100m pa Funding for councils to invest in infrastructureEconomic and fiscal update
Budget 2025: The switch-it budget
Thu 22 May 2025
Core crown revenue down $9.8b, and expenses down $3.1b Return to surplus in 2028/29Investment Boost tax incentive to drive investment