Major conflict has broken out in the Middle East, following Israeli and US airstrikes against Iran, and followed by retaliation by Iran against both countries, as well as others in the region.
Middle East plunged into a wider regional conflict
The conflict was initiated by Israeli and US airstrikes against Iran as part of Operation Epic Fury, which was followed by retaliation by Iran against both countries, as well as others in the region, including Saudi Arabia, Bahrain, Kuwait, Qatar, and the United Arab Emirates (UAE).
US officials, and US President Donald Trump, have variously stated that their aim is to destroy Iran’s weapons capability, stop Iran’s nuclear programme, and force regime change. Stated timeframes from Israel and the US indicate a 2-4 week long bombing campaign, although timeframes remain uncertain.
Various senior Iranian military and political leaders have been killed, including Iran’s Supreme Leader, Ayatollah Ali Khamenei. In retaliation, Iranian missile and drone strikes have hit various targets in the region, including military bases, diplomatic and spy posts, and airport and shipping hubs. These strikes have included civilian areas (including a hotel) in Abu Dhabi and Dubai.
A wide-ranging, uncertain, economic impact
In our view, there are a few key economic effects for New Zealand. In order of relative importance, they are as follows.
- Energy costs – oil prices are the key focus, both internationally and for New Zealand, although the closure of QatarEnergy’s LNG production – which represented 20% of global gas supply – is also worrying. More on the energy price shock shortly.
- Travel – key airports in the Middle East have been heavily disrupted, affecting some of the world’s busiest airports and airlines, with airspace closed, airports under attack, or flights unable to travel due to missile and drone attack risks. Cirium data shows over a million disrupted passengers. Stats NZ data shows there are 124 flights a month between New Zealand and Dubai directly, making it the seventh-largest long-haul flight destination from New Zealand (excluding Australian and Pacific Island ports). Many other routes fly indirectly to or through Dubai, as well as to or through Doha (Qatar) and Abu Dhabi (UAE).
- Trade – New Zealand exported $3.25b to Gulf Cooperation Council (GCC) countries over the 12 months to September 2025, with Saudi Arabia, the UAE, and Oman the top three countries in the area. Together, the GCC countries were New Zealand’s sixth largest export destination. The majority of our exports to the region were dairy, at $2.2b, with some meat ($260m).
- Investments – conflict is generally bad for businesses, although the investment reaction has been muted for now. Since last Friday (pre-conflict), the S&P500 has dipped 0.9%.
Fuel price surge surprisingly muted
Oil prices usually surge higher during periods of Middle Eastern conflict, with worries about the supply of oil from the area, a key oil-producing region. Around 20% of the world’s oil moves through the narrow Strait of Hormuz between Iran and the UAE, and threats over access to the Strait, or to shipping, can have major implications on oil prices and shipping rates.
Oil prices had already increased slightly during February, before the conflict began, reflecting heightened risk of conflict as the US moved substantial military assets into the region. Dubai crude oil prices – the reference oil price that matters for New Zealand – had increased to US$68/bl in mid-February, to the highest levels since late September 2025, amid continued Middle East tensions.
Oil prices have now surged further, with Brent oil prices – the international oil reference price – increasing around 16% since the conflict began (see Chart 1), after Iran closed the Strait of Hormuz and shipping was attacked. Substantial ship numbers are holding fast outside the Strait, with war risk insurance coverage being cancelled and repriced substantially higher, or cancelled outright. Despite assertions by US President Trump that the US will provide insurance to shipping, and also undertake navel escorts through the Strait, the disruption in oil and general trade flows is enormous.
However, the initial reaction to conflict erupting was more muted than we’d expected, and even now, oil prices only going to around $85/bl seems a limited response. Some market analysts anticipate that international oil prices could rise to US$90-$100/bl, given the ongoing conflict and uncertainty over security of supply for oil products. We remain concerned about the risk that oil prices could rise further, and that the market might be undercooking the current disruption.
Last year’s US airstrikes in Iran as part of Operation Midnight Hammer had a limited effect on oil prices – the strikes were more surgical and targeted at nuclear facilities. Military action at the time was over quickly, didn’t strike oil facilities, and didn’t escalate into wider conflict or attacks on other parts of the region – especially not against other major oil-producing nations. We think this time is different. The conflict has directly affected the Strait this time, and the wider regional conflict has hit other oil-producing nations in the region that weren’t drawn into previous conflicts in the region. Additionally, current military action is expected to last weeks, rather than hours. The situation is still fluid, but with actual oil supply impacts, a wider regional scope, and more unpredictability with a changing Iranian leadership, all bets are off.
A fuel shock…
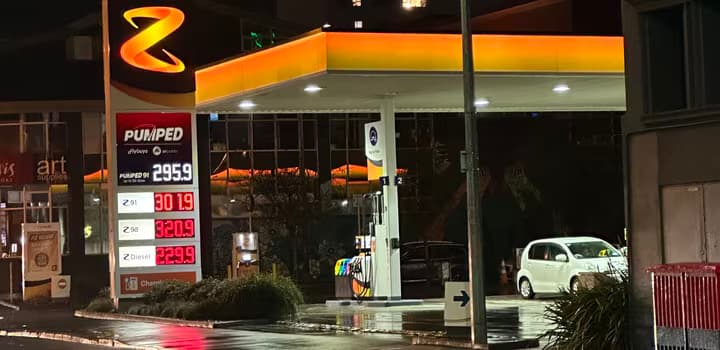
Domestic fuel prices are set to rise in response to higher international oil prices, probably within the next week. Although New Zealand holds around a month of fuel stores, prices usually react quickly. Such an increase would raise both consumer costs and business costs for transport. The NZ dollar has fallen nearly 1c against the US dollar, to around US59c, which will amplify any higher international oil prices too.
At around the US60c mark, oil prices increasing by the amount they have so far are set to add perhaps 38c/L to domestic fuel prices compared to where they were last week, to sit at around $2.91/L. At around US$100/bl, petrol prices in New Zealand would start to hit around $3.24/L.
… that RBNZ could look through, although it would hit already stretched inflation tolerance
The Reserve Bank had warned of conflict, and the chance of geopolitical risks impacting inflationary outcomes. The Bank’s February Monetary Policy Statement forecast oil prices to pick up to a quarterly average of US$69/bl for Dubai crude in the June 2026 quarter, then moderate back to around US$66/bl from the end of this year. And usually, the Bank “looks through” oil price shocks, given they represent an external supply shock that can lead to weaker demand conditions and slower economic growth. Household budgets are typically squeezed by having to pay more to fill up the car, leaving less money for spending on other goods and services.
But with headline inflation already higher than hoped, increased fuel prices could hamper efforts to drag inflation back towards 2%pa this year as is forecast. That risk is particularly acute from the second-round effect of higher oil prices. The first-round effect is higher fuel prices for households. But the second-round effect is higher transport costs for a wider set of goods, and if other businesses then seek to pass those increased transport costs on in their prices, then wider inflationary pressures could start to build.